A corporate travel card is a company issued payment card that employees use to cover business travel costs like flights, hotels, meals, and transportation. It centralizes expense tracking, often includes travel perks like airport lounge access, and removes the need for employees to front their own money on business trips.
Nobody enjoys standing at an airport counter watching a personal credit card get charged for a flight that won’t be reimbursed for weeks. That’s the everyday frustration many business travelers face without the right tools in place. A corporate travel card solves this problem by letting employees pay for trip expenses directly through company funds, while giving finance teams real time visibility into spending.
If someone is a frequent flyer jetting between New York and Los Angeles for client meetings, or a small business owner sending a team to a conference in Chicago, understanding how these cards work can save time, reduce stress, and protect both the traveler and the company. This guide breaks down everything from how corporate travel cards function to how to choose the right one, use it responsibly on the road, and avoid common pitfalls.
What Is a Corporate Travel Card and How Does It Work?
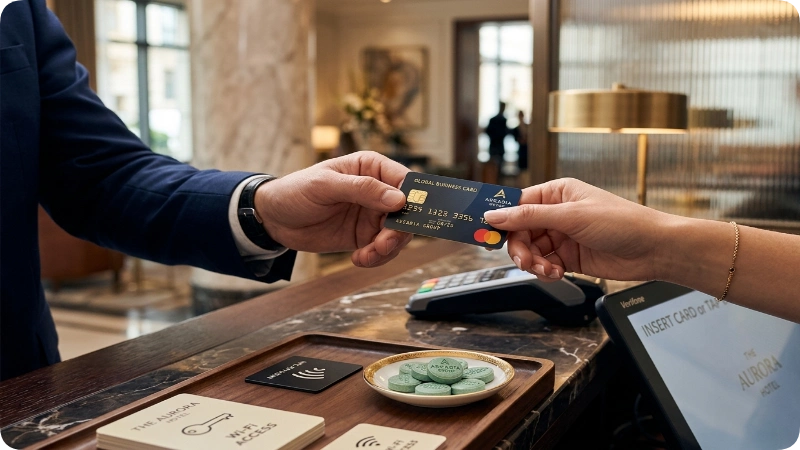
A corporate travel card is issued by a company to employees specifically for business travel and related expenses. Unlike a personal credit card, the bill goes to the employer, not the individual, and spending is usually tracked through an integrated expense management platform. Most cards sync with software like Concur, Expensify, or Ramp so receipts and categories are logged automatically.
Who Issues These Cards?
Corporate travel cards are typically issued through banks or fintech providers such as American Express, Chase, Capital One, Brex, or Ramp. Some airlines and hotel chains also partner with these providers to layer on travel specific rewards, like bonus points on flights or complimentary hotel status.
Centralized vs. Individual Card Programs
Some companies use one central card managed by a travel coordinator, while others issue individual cards to each traveling employee. Individual cards tend to offer better accountability and faster reimbursement free spending, while centralized cards work well for smaller teams with infrequent travel.
Corporate Travel Card vs. Personal Card vs. Prepaid Card
Choosing the right payment method for business travel depends on company size, travel frequency, and how much control finance teams want over spending. The table below breaks down the key differences.
| Feature | Corporate Travel Card | Personal Card (Reimbursed) | Prepaid Travel Card |
| Who pays upfront | Company | Employee | Company (preloaded) |
| Reimbursement wait | None | Days to weeks | None |
| Spending controls | Yes, adjustable limits | No | Yes, fixed balance |
| Rewards ownership | Usually the company | Usually the employee | Rarely offered |
| Best for | Frequent business travel | Occasional, low cost trips | Contractors or interns |
Types of Corporate Travel Card Programs
Not every corporate travel card works the same way. Before choosing a program, it’s important to understand who is legally responsible for paying the bill and how expenses are managed.
Individual Liability Cards
The employee receives the statement and pays the balance first, then submits expenses for reimbursement. Many large organizations use this model because it encourages timely expense reporting while giving employees responsibility for the account.
Corporate Liability Cards
The company receives and pays the statement directly. Employees simply use the card for approved travel expenses and submit receipts through the expense management system.
Joint Liability Cards
Some organizations share responsibility. The employer pays approved business expenses, while employees remain responsible for any personal or unauthorized purchases.
Understanding which model your employer uses helps avoid confusion about payment deadlines, reimbursements, and credit reporting.
Who Should Use a Corporate Travel Card
Corporate travel cards work best for companies with employees who travel regularly for client visits, conferences, or multi city sales trips. They’re especially useful for teams of five or more frequent travelers, since the administrative savings on expense tracking quickly outweigh the setup effort.
Who Should Consider Alternatives
Very small businesses with only occasional travel, such as one trip per quarter, may find a simple reimbursement policy easier to manage than a full card program. Startups with tight cash flow should also compare secured or prepaid options before committing to a credit based program with a large credit line.
Key Benefits of Corporate Travel Cards
Corporate travel cards remove the financial burden from employees, speed up expense reporting, and often unlock travel perks unavailable on personal cards. Below are the advantages that matter most to frequent business travelers.
- No out of pocket spending employees don’t wait for reimbursement on flights or hotels
- Real time expense tracking finance teams see spending as it happens, not weeks later
- Travel rewards and perks many cards offer airport lounge access, free checked bags, or hotel status
- Built in travel insurance many corporate cards include trip cancellation or delay coverage
- Fraud protection company level monitoring catches suspicious charges faster than personal accounts
Features to Look for When Choosing a Corporate Travel Card
Not all business travel cards provide the same value. Companies should compare features beyond rewards programs.
Look for:
- No foreign transaction fees
- Real-time spending notifications
- Virtual card generation
- Mobile wallet compatibility
- Receipt capture through the issuer’s app
- Integration with expense software
- Flexible spending controls
- Fraud monitoring
- 24/7 travel assistance
- Travel insurance benefits
- Airport lounge access (if valuable for frequent travelers)
- Multi-currency support for global businesses
Choosing the right features often saves more time than chasing the highest rewards rate.
Common Drawbacks to Know Before Signing Up
No card is perfect, and it helps to understand the trade offs before a company commits to a program. The most common complaints involve rigid spending categories, delayed card issuance for new hires, and rewards points that belong to the company rather than the traveling employee.
Some employees also report friction when a card is declined mid trip due to unusual spending patterns, such as a large hotel deposit or a rental car hold. Travelers should always carry a backup payment method for these situations, especially internationally.
How to Get a Corporate Travel Card as an Employee
Employees typically receive a corporate travel card through their company’s finance or HR department after completing a short application and agreeing to the company’s travel and expense policy. The process usually takes a few business days.
- Confirm eligibility with HR or the finance department
- Complete the card issuer’s employee application
- Review and sign the company travel and expense policy
- Activate the card through the issuer’s app or website
- Link the card to the company’s expense management software
Understanding Spending Limits and Controls
Most corporate travel cards allow administrators to set daily, monthly, or per trip spending limits, and some can even restrict purchases to specific categories like airfare and lodging. This prevents overspending while still giving travelers flexibility during their trip.
Real Time Alerts
Many providers send instant notifications to both the employee and the finance team when a charge is made, which helps catch billing errors like duplicate hotel charges or incorrect currency conversions before they become bigger problems.
How Corporate Travel Cards Help Finance Teams
Corporate travel cards aren’t just useful for employees—they also simplify work for finance departments.
Benefits include:
- Automated expense categorization
- Faster monthly reconciliation
- Reduced reimbursement processing
- Better policy compliance
- Real-time spending visibility
- Easier tax and audit preparation
- Centralized reporting across departments
- Improved budget forecasting
For organizations with frequent travel, these efficiencies can significantly reduce administrative workload while improving financial oversight.
How to Use a Corporate Travel Card Responsibly
Responsible use protects both the traveler’s reputation and the company’s bottom line. Employees should treat the card strictly for approved business expenses and keep digital copies of every receipt for audit purposes.
- Save receipts immediately using the expense app’s photo upload feature
- Separate personal purchases from business ones, even at the same hotel
- Note the business purpose of every meal or entertainment charge
- Avoid using the card for cash advances unless specifically authorized
- Report a lost or stolen card to the issuer within minutes, not hours
Corporate Travel Card Rewards and Points Programs
Many corporate travel cards earn points or miles on every purchase, but company policy usually determines who keeps them. Some employers let frequent travelers retain personal loyalty points from airlines and hotels even while the company covers the bill, which is worth confirming before booking.
Stacking Personal Loyalty Numbers
Travelers can often add their personal frequent flyer or hotel loyalty number to a corporate card booking, earning personal status points even though the company pays. This is one of the most underrated perks of business travel and costs nothing extra.
Corporate Travel Card vs. Business Credit Card
Although the terms are sometimes used interchangeably, a corporate travel card and a business credit card serve different purposes. A corporate travel card is designed primarily for employee travel expenses and usually includes spending controls, expense management integrations, and travel-related benefits. A business credit card offers broader purchasing flexibility for everyday business expenses like office supplies, advertising, or software subscriptions.
| Feature | Corporate Travel Card | Business Credit Card |
| Primary purpose | Employee travel expenses | General business spending |
| Spending controls | Extensive | Varies |
| Expense software integration | Usually included | Sometimes |
| Employee cards | Yes | Yes |
| Travel benefits | Extensive | Varies |
Companies with frequent business travel often use both products together rather than choosing one over the other.
Booking Flights and Hotels with a Corporate Travel Card
Corporate travel cards can be used directly through airline and hotel websites, but many companies require bookings through a designated travel management platform to keep pricing compliant with negotiated corporate rates. Booking outside the approved system can sometimes void certain card protections.
Airports like Hartsfield Jackson Atlanta International, Chicago O’Hare, and Dallas Fort Worth are major connection hubs for business travelers, and many corporate travel programs negotiate preferred rates with airlines operating heavily out of these hubs, such as Delta, United, and American Airlines.
What Expenses Can You Put on a Corporate Travel Card?
Most organizations define exactly which purchases are considered business travel expenses.
Common approved purchases include:
- Flights
- Hotels
- Rental cars
- Rideshare services
- Taxis
- Parking
- Fuel for rental vehicles
- Business meals
- Conference registration
- Airport baggage fees
- Public transportation
- Internet charges required for work
Usually not allowed:
- Alcohol (depending on policy)
- Personal shopping
- Family expenses
- Entertainment unrelated to business
- Cash withdrawals without approval
- Vacation costs added to business trips
Employees should review company policy before assuming an expense is reimbursable.
Using a Corporate Travel Card Internationally
International trips require extra planning since foreign transaction fees, currency conversion, and fraud alerts can all affect how smoothly a corporate card performs abroad. Confirm with the card issuer If foreign transaction fees apply, since many premium corporate cards waive them entirely.
Notify the Issuer Before Departure
Some providers still flag international charges as suspicious even with modern fraud detection. It’s smart practice to notify the card issuer of travel dates and destinations before departure, similar to a personal credit card, to avoid a declined charge at a critical moment like check in.
International Business Travel Checklist
Before leaving the United States, take a few minutes to confirm everything is ready.
Checklist:
- Notify the card issuer of travel dates (if recommended)
- Verify foreign transaction fees
- Confirm daily spending limits
- Save the emergency support number
- Enable travel notifications in the issuer’s app
- Download offline copies of receipts
- Carry one backup payment method
- Verify PIN requirements for chip-and-PIN countries
- Understand local tipping customs
- Confirm reimbursement rules for foreign currency purchases
Five minutes of preparation can prevent hours of frustration overseas.
Common Mistakes Business Travelers Make with Corporate Cards
Even experienced travelers slip up occasionally, and a few mistakes show up more often than others.
- Mixing personal and business charges always use a separate card for personal purchases, even small ones
- Forgetting receipts snap a photo immediately instead of relying on memory later
- Ignoring the travel policy booking outside preferred vendors can trigger reimbursement delays or denials
Safety and Fraud Protection Tips
Corporate travel cards generally include stronger fraud monitoring than personal cards because transactions are reviewed by both the bank and the company’s finance system. Still, travelers should take a few precautions on the road.
- Use tap to pay or chip transactions instead of card swipes where possible
- Avoid public Wi Fi when checking card balances or expense apps
- Keep the issuer’s fraud hotline saved in a phone, not just in an email
- Report anything unusual immediately rather than waiting until returning home
What to Do If Your Corporate Travel Card Is Lost or Stolen
Losing a payment card during a business trip is stressful, but acting quickly minimizes disruption.
If your card disappears:
- Lock the card using the issuer’s mobile app if available.
- Contact the issuer’s emergency support line immediately.
- Notify your company’s finance or travel department.
- Review recent transactions for unauthorized charges.
- Request emergency card replacement if you’re still traveling.
- Keep copies of any fraud reports for company records.
Many major issuers can arrange expedited replacement cards within one or two business days, depending on your location.
Corporate Travel Card Policies Every Employee Should Read
Every company sets its own rules for what’s covered, from meal per diem to acceptable hotel star ratings. Reading the travel and expense policy before the first trip prevents awkward conversations with finance later and helps travelers understand exactly what “reasonable and necessary” spending means at their organization.
Tax and Expense Reporting Considerations
Corporate travel cards simplify expense reporting, but employees are still responsible for following company documentation requirements. Most businesses require receipts, business purposes, attendee names for client meals, and timely expense submissions to remain compliant with internal accounting policies and applicable tax regulations.
Finance teams may reject incomplete expense reports or request additional documentation during audits. Keeping digital copies of receipts throughout the trip makes reconciliation much easier once you return.
Alternatives to a Traditional Corporate Travel Card
Not every business needs a full card program right away. Virtual cards, which generate a unique number for each booking, are increasingly popular for one time vendor payments like conference registrations. Prepaid business cards work well for contractors who need spending limits without a credit check, while simple reimbursement policies remain practical for companies with minimal travel volume.
How to Choose the Best Corporate Travel Card for Your Company
The best card depends on company size, travel frequency, and financial processes rather than rewards alone.
Small businesses often benefit from straightforward programs with low fees and simple expense tracking.
Growing companies should prioritize automation, accounting software integrations, and customizable spending controls.
Large enterprises typically value centralized reporting, negotiated travel benefits, advanced policy enforcement, and dedicated account management.
Evaluating operational efficiency alongside travel perks usually delivers greater long-term value.
Is a Corporate Travel Card Worth It?
For companies with regular business travel, a corporate travel card is generally worth the setup effort because it saves administrative time, improves expense accuracy, and removes financial strain from employees. Companies with rare or minimal travel may find the overhead unnecessary compared to a straightforward reimbursement process.
What’s overrated: premium card perks like airport lounge access matter less than reliable customer support when a card gets declined abroad. What’s underrated: real time spend alerts, which catch billing mistakes long before a monthly statement ever arrives.
Signs It’s Time to Upgrade Your Company’s Travel Card Program
As a business grows, its travel needs often outgrow a basic reimbursement system.
Consider upgrading if your company experiences:
- Frequent employee travel
- Delayed reimbursements
- Manual expense reporting
- Difficulty tracking travel budgets
- Increasing finance workload
- Multiple employees sharing one card
- Poor visibility into travel spending
- Growing international travel
Modern travel card platforms can automate many of these tasks while improving policy compliance.
Corporate Travel Card Best Practices
Companies that get the most value from corporate travel cards usually follow a few consistent habits.
Best practices include:
- Issue written travel policies.
- Require receipt uploads within 24 hours.
- Review spending reports regularly.
- Set appropriate spending limits by employee role.
- Train new travelers before issuing cards.
- Audit expenses periodically.
- Encourage travelers to report lost cards immediately.
- Review card programs annually to ensure they still meet company needs.
Strong policies protect both employees and the business while reducing administrative work.
FAQs
What is a corporate travel card used for?
A corporate travel card covers business trip expenses like flights, hotels, rental cars, and meals, billed directly to the company instead of the employee. It removes the need for upfront personal spending and simplifies expense reporting through connected software.
Can employees keep corporate card reward points?
It depends entirely on company policy. Some employers allow employees to keep airline or hotel loyalty points earned personally, even when the company covers the actual cost through the corporate card.
Do corporate travel cards affect personal credit scores?
Most corporate travel cards are issued under the company’s credit profile, not the employee’s personal credit, so responsible or irresponsible use typically doesn’t appear on a personal credit report. Always confirm this with the specific card issuer.
What happens if a corporate travel card is declined?
Employees should contact the card issuer’s support line immediately and have a backup payment method ready, such as a personal card, to avoid disruption during check in or checkout.
Are corporate travel cards safe to use internationally?
Yes, most include fraud monitoring and travel insurance, but employees should notify the issuer of travel dates beforehand and confirm If foreign transaction fees apply before departure.
How is a corporate travel card different from a company credit card?
A corporate travel card is often a specific type of company credit card restricted to travel related categories, while a general company credit card may allow broader purchases like office supplies or software subscriptions.
Who is responsible if a corporate travel card is misused?
Responsibility depends on the company’s travel policy, but most agreements state that non business charges become the employee’s personal responsibility to repay, even though the company technically holds the account.
Can contractors receive a corporate travel card?
Yes, some companies issue corporate travel cards to contractors, consultants, or temporary workers, but it depends on the organization’s travel policy and the card provider’s requirements. Many businesses prefer prepaid or virtual corporate cards for contractors because they offer tighter spending controls and lower financial risk. If a physical corporate card isn’t available, contractors are often reimbursed for approved travel expenses after submitting receipts.
Can I use a corporate travel card for personal expenses and reimburse the company later?
Generally, no. Corporate travel cards are intended only for authorized business expenses, and using one for personal purchases may violate your company’s travel and expense policy. Even if you plan to repay the company, unauthorized personal charges can trigger audits, reimbursement issues, or disciplinary action. If an accidental personal purchase occurs, notify your finance or HR department immediately and follow the company’s process for repaying the expense.
Do corporate travel cards include rental car insurance?
Many corporate travel cards include rental car insurance, but the level of protection varies by issuer and card program. Some cards provide secondary collision damage coverage, while premium travel cards may offer primary coverage when you pay for the rental with the card and decline the rental company’s collision damage waiver. Coverage often excludes certain vehicle types, countries, or commercial use, so review your card’s Guide to Benefits or confirm the details with the issuer before relying on this protection.
Corporate Travel Card Checklist
Before your next business trip, make sure you’ve completed these steps.
| Task | Complete |
| Corporate card activated | ✓ |
| Expense app installed | ✓ |
| Company travel policy reviewed | ✓ |
| Spending limits confirmed | ✓ |
| Backup payment method packed | ✓ |
| Emergency support number saved | ✓ |
| Loyalty accounts linked | ✓ |
| Receipts uploaded during trip | ✓ |
Following a simple checklist helps prevent avoidable issues and keeps expense reporting quick after returning home.
Final Takeaways
A corporate travel card genuinely changes the way business travel feels, replacing reimbursement stress with a simple tap and go experience. The right program balances employee flexibility with company oversight, backed by clear policies everyone actually reads. Before the next business trip, it’s worth checking in with HR or finance to confirm current card policies, spending limits, and travel perks, since these details change often and are best verified directly with the provider. Business travel is smoother when the money side just works freeing up energy for the meetings, cities, and connections that actually matter.